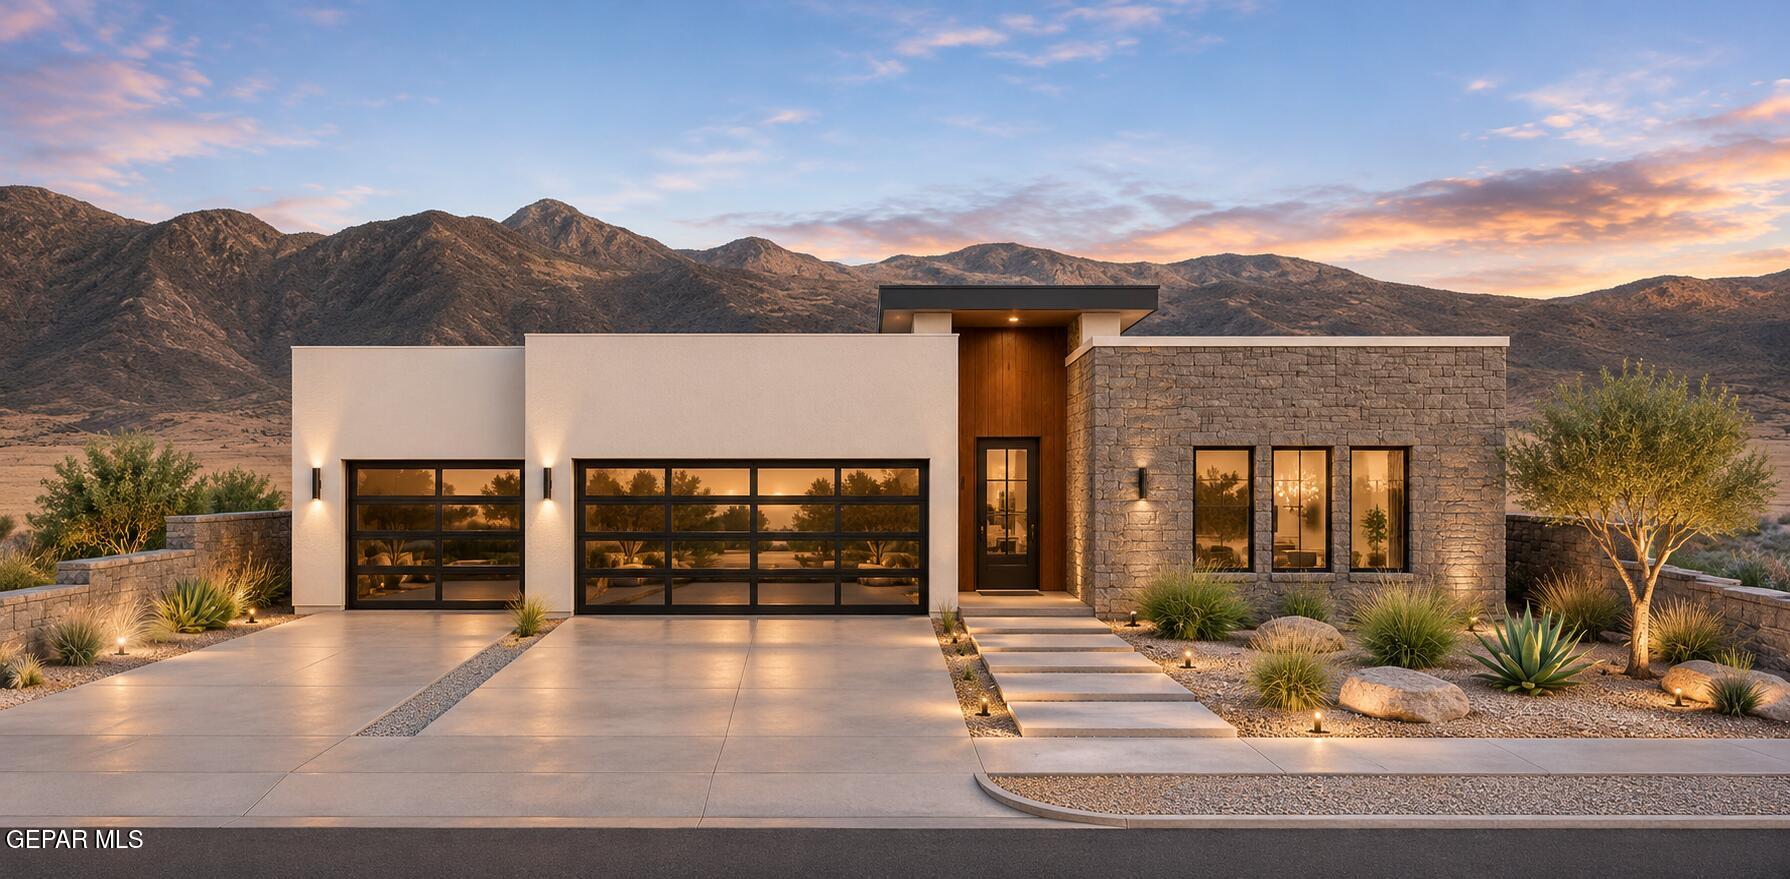
 Just listed
$769,000
West Side
7220 CIMARRON RIM Drive
El Paso, TX 79911
- 4 beds
- 3 baths
- 2,842 sqft
Episode 04
New Construction · 6 min read
El Paso home builders regularly offer incentives worth $5,000 - $25,000+ - including closing cost assistance, interest rate buydowns, appliance packages, and upgrade credits. The catch: many of the best incentives are tied to using the builder's preferred lender. Understanding the full picture before you sign lets you capture real value - and spot offers that aren't as good as they appear.
Production builders in El Paso (CareFree Homes, Hakes Brothers, Pacifica, and others) have a specific financial challenge: protecting their price sheet.
A builder who drops the base price of a home by $10,000 creates a new "comp" in their community - every future sale in that phase is now affected. Instead, builders prefer to offer incentives equal in value to a price reduction - closing cost assistance, upgrades, buydowns - that don't directly lower the contract price.
This is actually good for buyers who know how to negotiate, because the builder's willingness to offer incentives often exceeds what you'd get from a price negotiation.
1. Closing Cost Assistance The most straightforward incentive. The builder pays a portion of your closing costs - often $5,000 - $15,000. This reduces the cash you need at closing.
Catch: Closing cost assistance is frequently contingent on using the builder's preferred lender. Evaluate the preferred lender's rate and terms before assuming the incentive is worth it.
2. Interest Rate Buydown The builder pays the lender upfront to reduce your interest rate - either permanently (permanent buydown) or for the first 1 - 3 years (temporary buydown, like a 2-1 buydown).
When a buydown is valuable: If you plan to stay in the home for at least 5 - 7 years, a permanent rate reduction makes sense. A 2-1 temporary buydown is most valuable if you expect your income to increase in years 1 - 2, making the payment spike at Year 3 manageable.
3. Appliance Package Builder includes refrigerator, washer, dryer, or other appliances - not always standard in new construction. Value: $2,000 - $6,000.
4. Upgrade Credits Spend a set amount on designer-selected upgrades (flooring, countertops, backsplash, cabinets) from the builder's design center at no additional cost. Value varies widely.
Caution on upgrade credits: Builders mark up design center upgrades significantly. A $5,000 upgrade credit at the builder's design center might buy $2,500 - $3,000 in actual material value at retail. Still worth having - but not worth overpaying for the home to get it.
5. Lot Premium Waivers Corner lots, cul-de-sac lots, and view lots typically carry $5,000 - $25,000 lot premiums. Near the end of a phase, builders sometimes waive or reduce these.
6. HOA Dues Paid Builder pays your HOA fees for the first year. Common in master-planned communities like Campo del Sol.
$769,0007220 CIMARRON RIM Drive4 bd · 3 ba · 2,842 sqft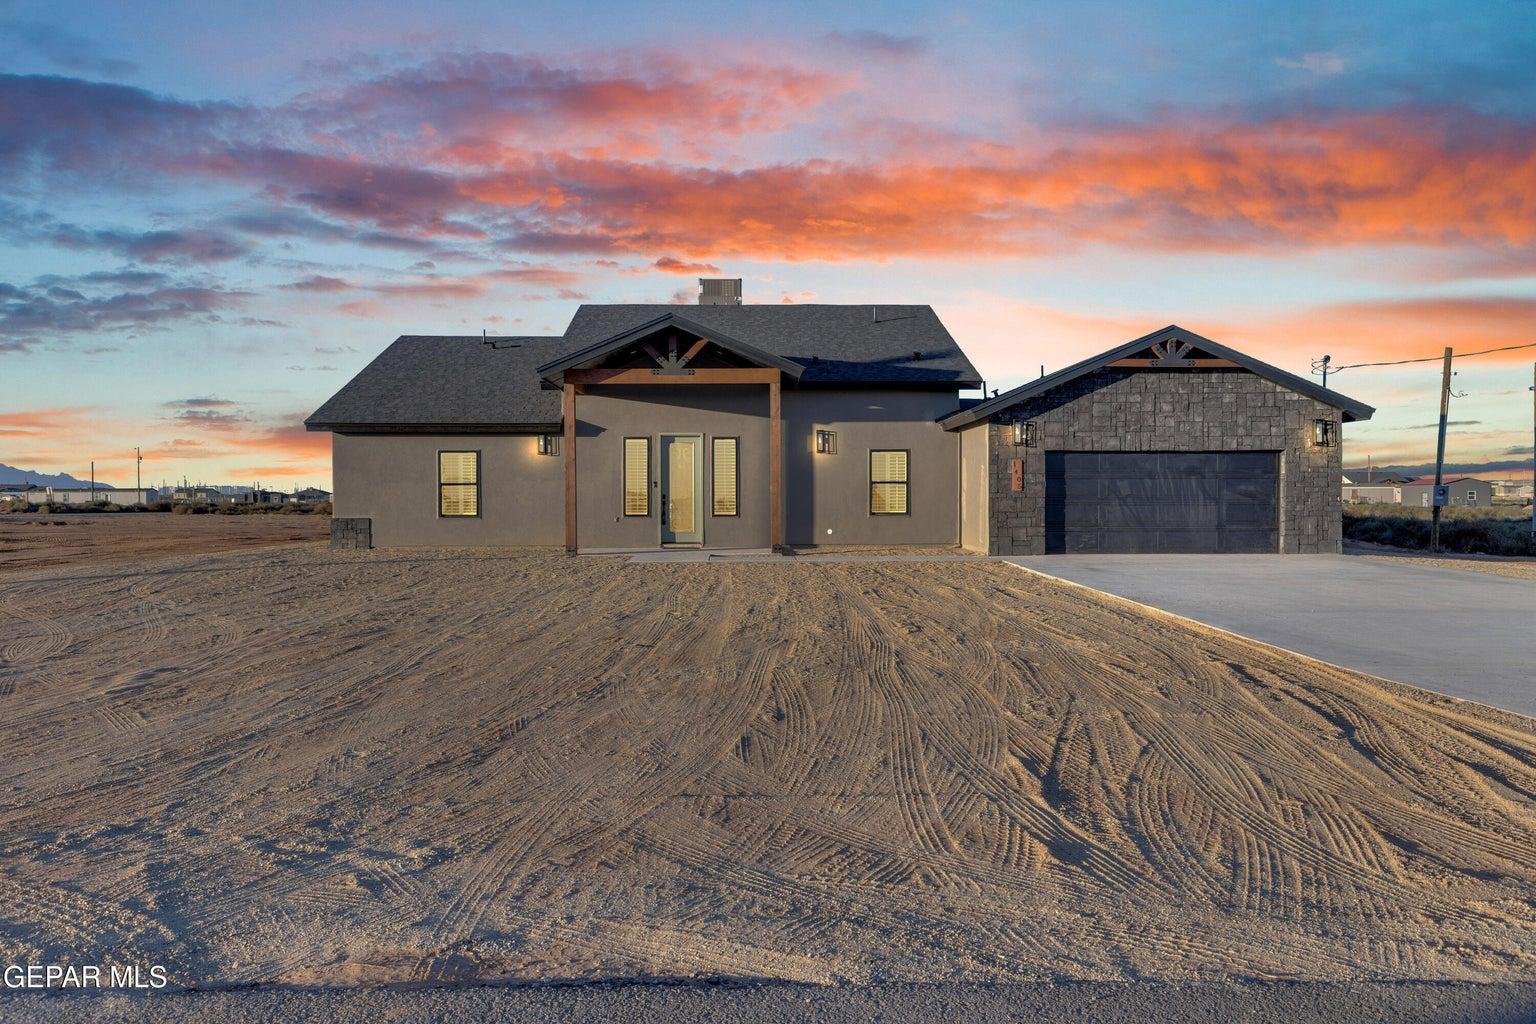 $489,0001405 NAMBI DESERT Drive4 bd · 3 ba · 2,329 sqft
 $275,00014724 Cactus Breeze Way4 bd · 2 ba · 1,482 sqft
Live from the El Paso MLS, newest first. Listings update hourly.
We'll watch the MLS for you and send the ones worth seeing. Unsubscribe with one tap.
End of quarter: Production builders have quarterly sales targets. The last 2 - 3 weeks of each quarter (end of March, June, September, December) are when salespeople have the most flexibility to offer incentives or get manager approval.
End of a phase: When a builder is completing one phase and opening the next, they may offer stronger incentives on the last remaining lots in the closing phase to clear inventory before the new release.
Slower seasons: November through January tends to be slower for El Paso new construction (fewer buyers are touring). Builders are more flexible on incentives during these periods.
This is the most important decision attached to incentives.
Why builders have preferred lenders: The builder's preferred lender is typically affiliated with or has a business relationship with the builder. The lender may offer streamlined construction tracking, but the primary purpose is to generate loan origination revenue for the builder's affiliated entity.
The conflict: The best incentives (closing cost assistance, rate buydowns) are frequently contingent on using the preferred lender. If you use an outside lender, you may lose $5,000 - $15,000 in assistance.
What to do: Get a competing quote from an independent VA-approved lender or mortgage broker before committing. Compare:
If the preferred lender's rate is 0.5% higher but the incentive is $10,000 in closing cost assistance, calculate the breakeven point. On a $270,000 loan, 0.5% rate difference = ~$90/month = $3,240 over 3 years. If you're staying longer than 3 years, the higher rate costs more than the incentive is worth.
VA buyers: If you're using a VA loan, your lender choice is especially important. Not all preferred lenders are well-versed in VA transactions. Using an inexperienced VA lender can cause delays, appraisal issues, or worse - losing your option period to a slow lender.
Yes. Everything is negotiable - but how you negotiate matters. Builders rarely reduce base prices. Instead, negotiate for additional closing cost assistance, rate buydown points, appliance packages, or upgrade credits. The end of a quarter or the end of a phase is your best leverage window.
Yes. Builder-paid closing cost assistance is compatible with VA loans. Builder-paid interest rate buydowns (discount points) are also VA-compatible, subject to VA rules. Confirm your specific incentive structure with your VA-approved lender before signing the purchase contract.
Not automatically. Get competing quotes first. If the preferred lender's rate is comparable to market and the incentive is substantial, using the preferred lender makes sense. If the preferred lender's rate is noticeably higher, the incentive may not compensate for the long-term cost.
A 2-1 buydown reduces your interest rate by 2% in year 1 and 1% in year 2, then returns to the full rate in year 3. It's worth it if: (a) the builder pays for it (not you), (b) you can handle the payment increase in year 3, and (c) you're comfortable that the full rate is a payment you can sustain. It's not worth it if it's being funded by a higher purchase price or reduced incentives elsewhere.
John David Peña | License #0733512 | Peña El Paso Realty Group | Brokered by Home Pros Real Estate Group | Broker License #9009766
Related Articles:
New Construction
A complete cost breakdown for building a custom home in El Paso - land, construction per square foot, permits, timeline, and how custom compares to buying from a production builder.
New Construction
Step-by-step guide to buying a new build in El Paso, choosing a builder, negotiating upgrades, inspections, timeline, and why you need your own realtor.
New Construction
Every active new construction community in El Paso organized by submarket - with builders, price ranges, amenities, and what makes each community different. Updated 2026.